
Fintech software development company for products built on regulated partners
Payments, lending and wealth platforms that leave card data, funds and licensed decisions with your bank, processor or lender.
- The regulated perimeter drawn before the architecture
- Tokenized checkout that keeps card numbers off your servers
- Every partner integration scoped before the price
 Reviewed by Mayursinh Jadeja, Founder · Last updated November 5, 2026
“The admin panel feels like it was made specifically for us, because it was.”
Trusted by clients around the globe


Why fintech builds stall
The perimeter decides what you can build, and what you must not hold
Most fintech delays come from data and decisions that should have stayed with a partner.
We draw the regulated perimeter on paper before the architecture: what your partners hold, what you hold, and what stays out by design.
- Card data that pulled you into PCI scopeA form posted card numbers to your server. Now every system is in scope.
- A partner who said no lateThe bank’s rules surfaced after the build, and features came out.
- Compliance staffed by nobodyKYC alerts and disputes pile up because no one owns them.
Case studies
Fintech software development case studies
Design work
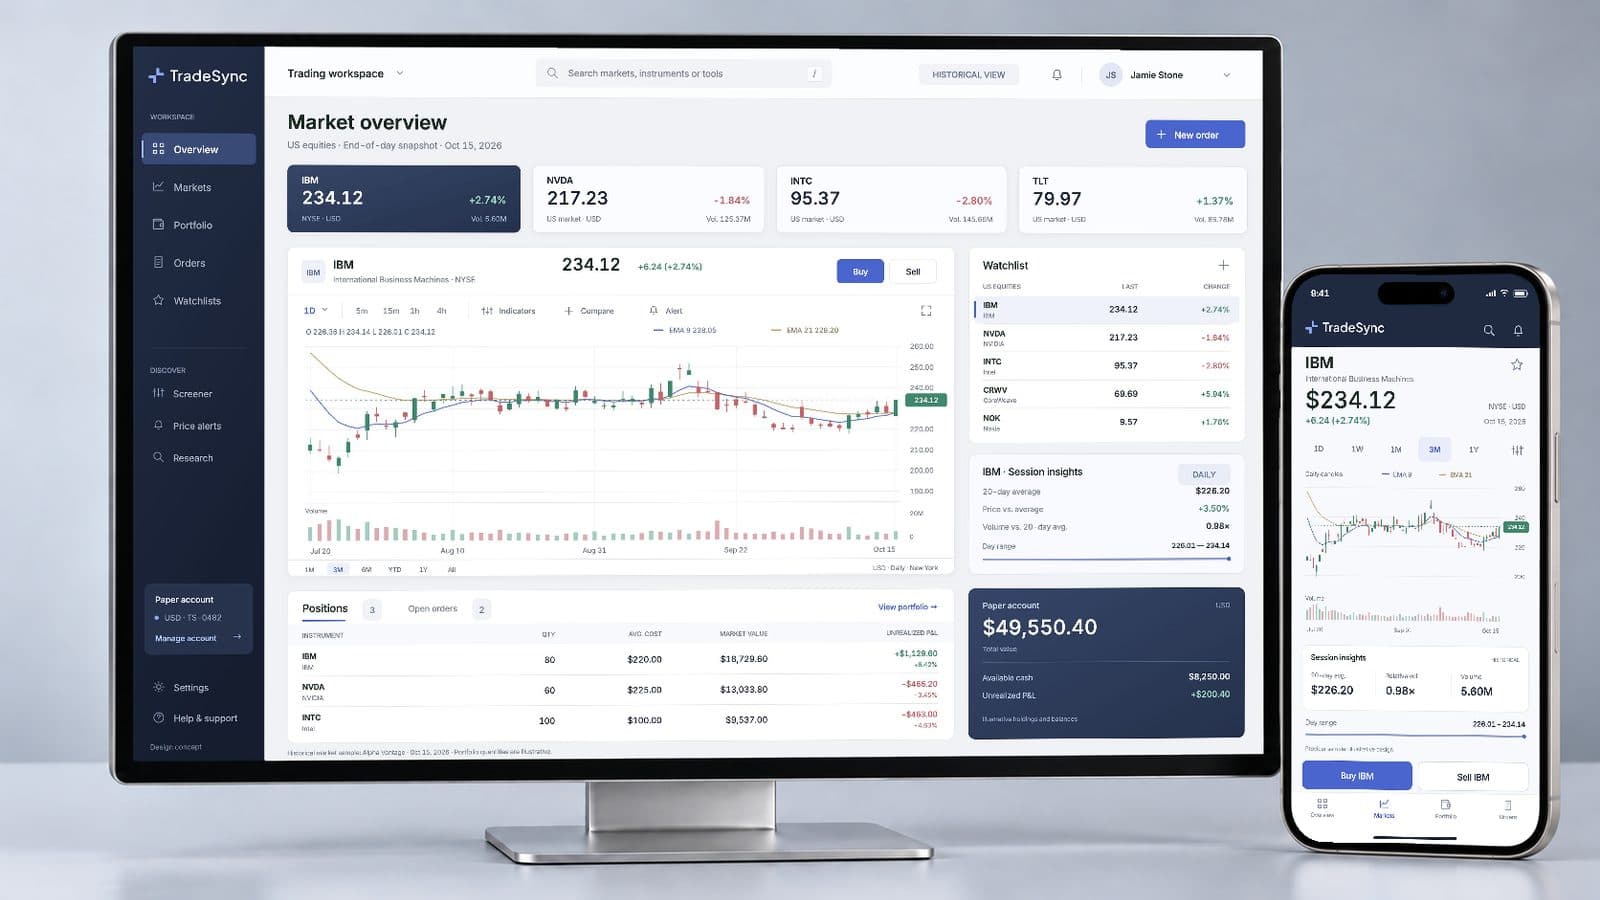
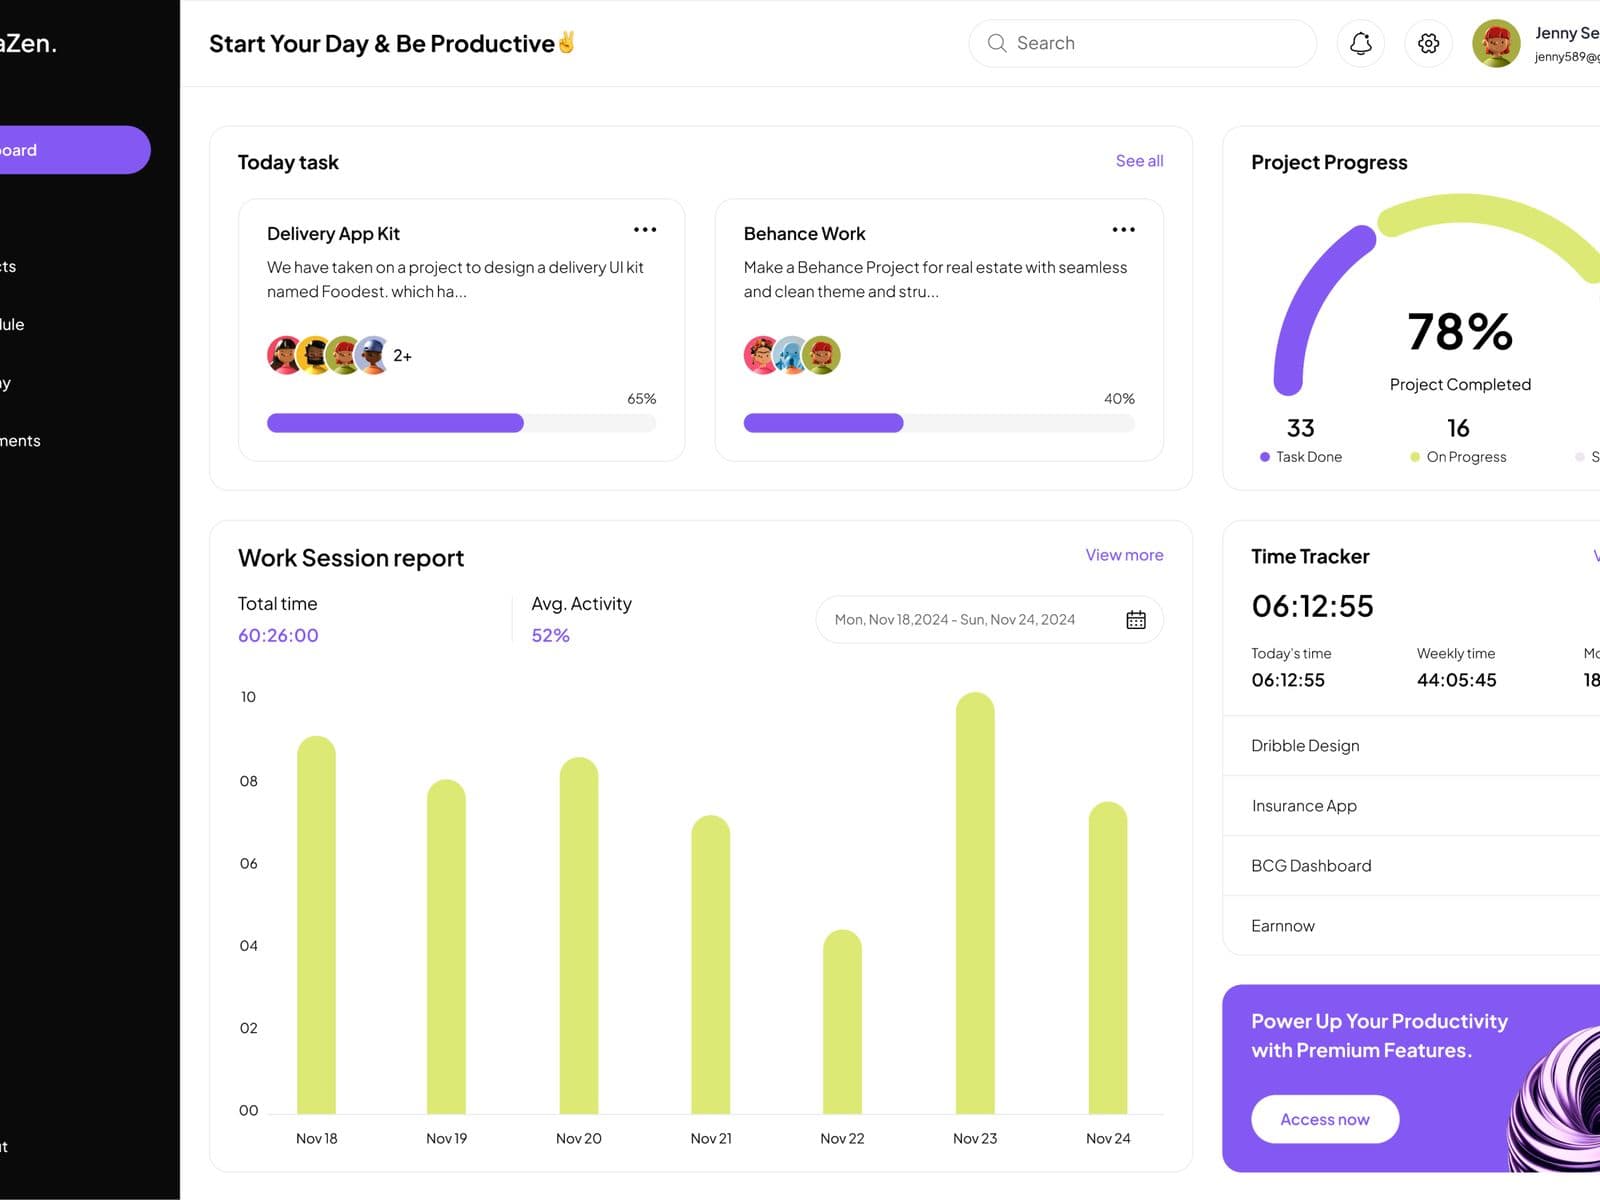
Trading platform development, from the UI out: TradeSync for tablet and desktop
A stock trading platform UI for tablet and desktop, and the build plan behind it.
Design work
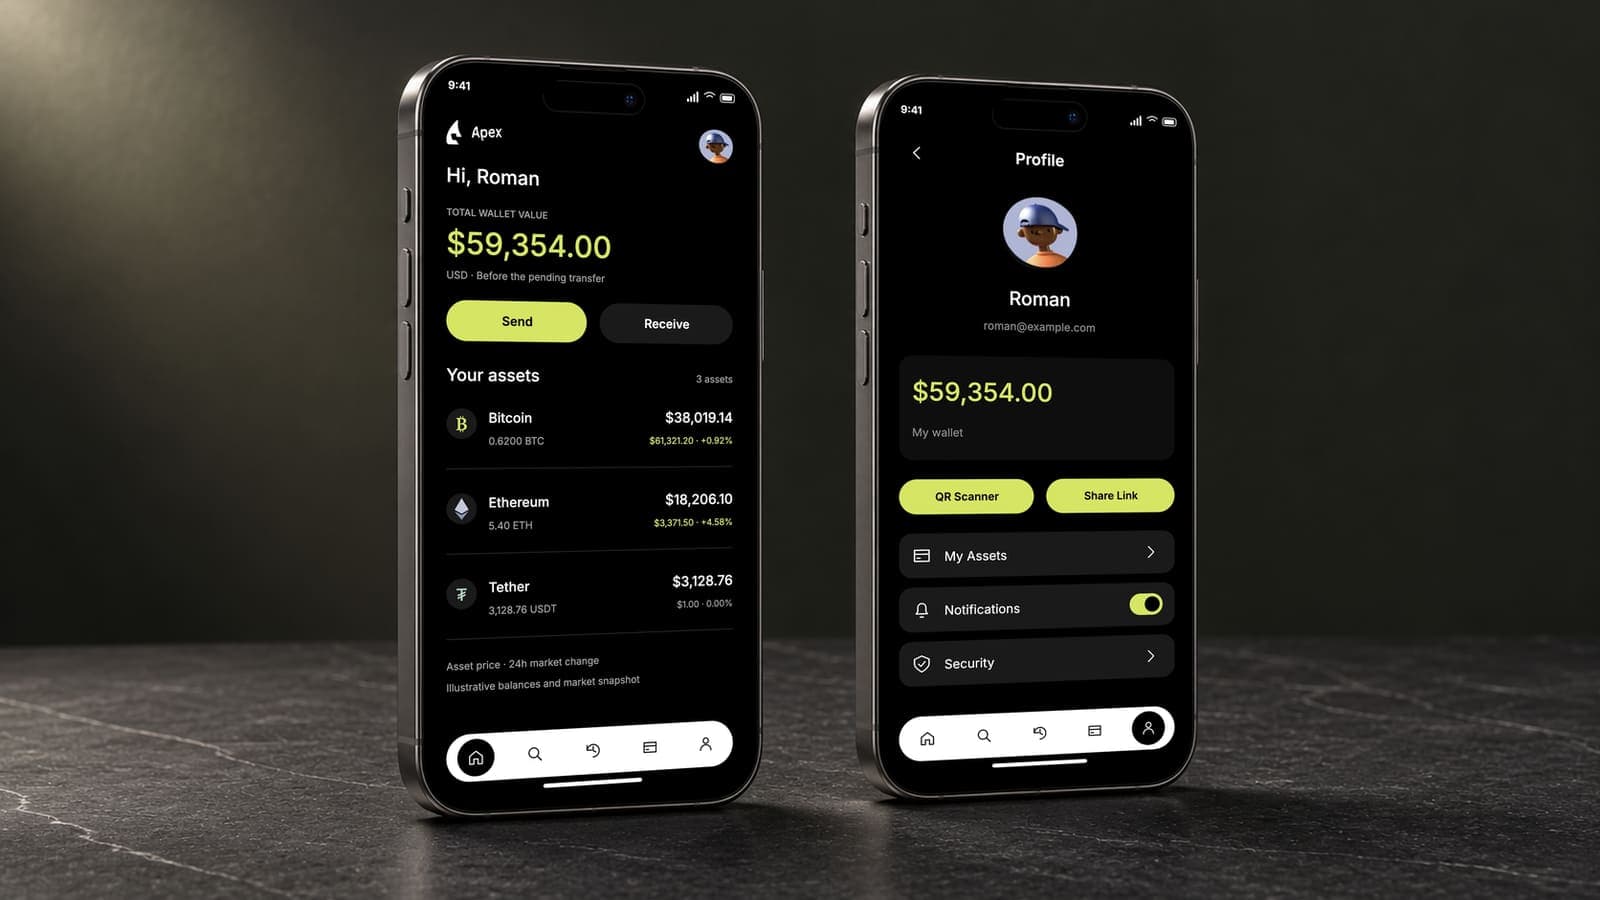
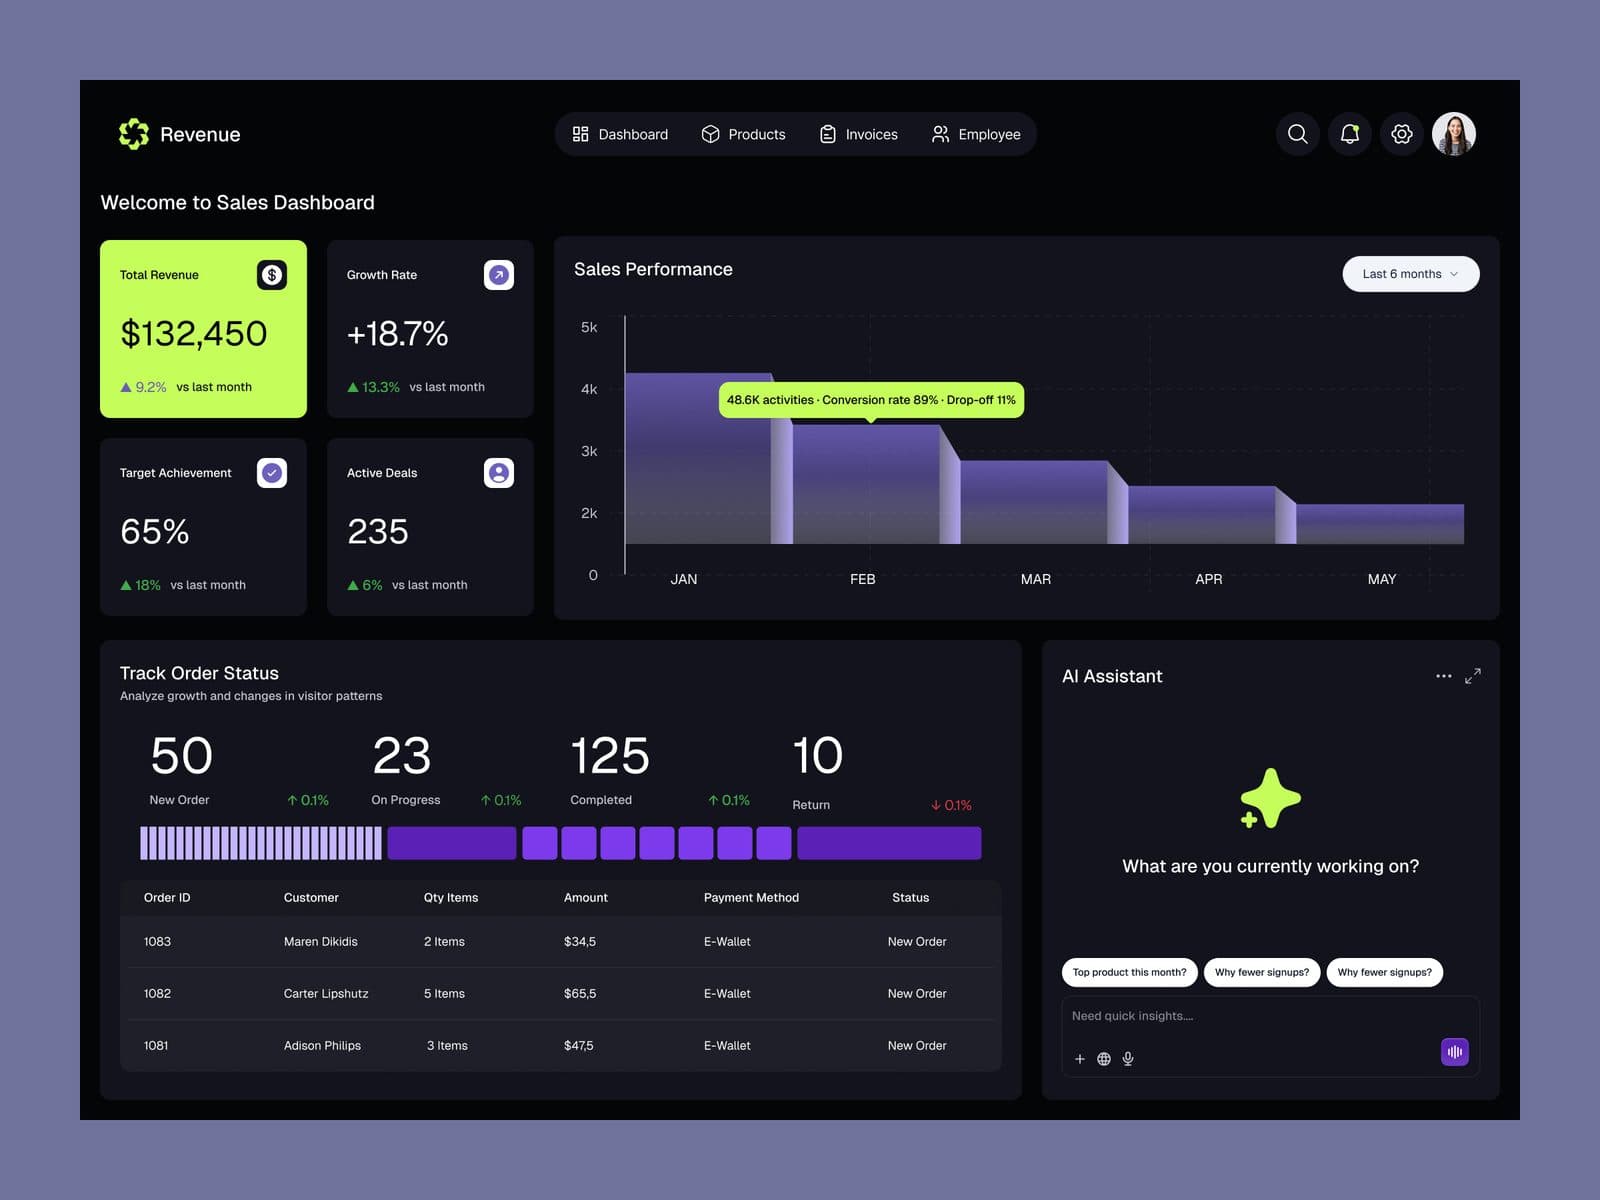
Crypto wallet app development, from the private key to the sent coin: Apex
A dark mode crypto wallet app, and the keys, chains and sending behind it.
Design work
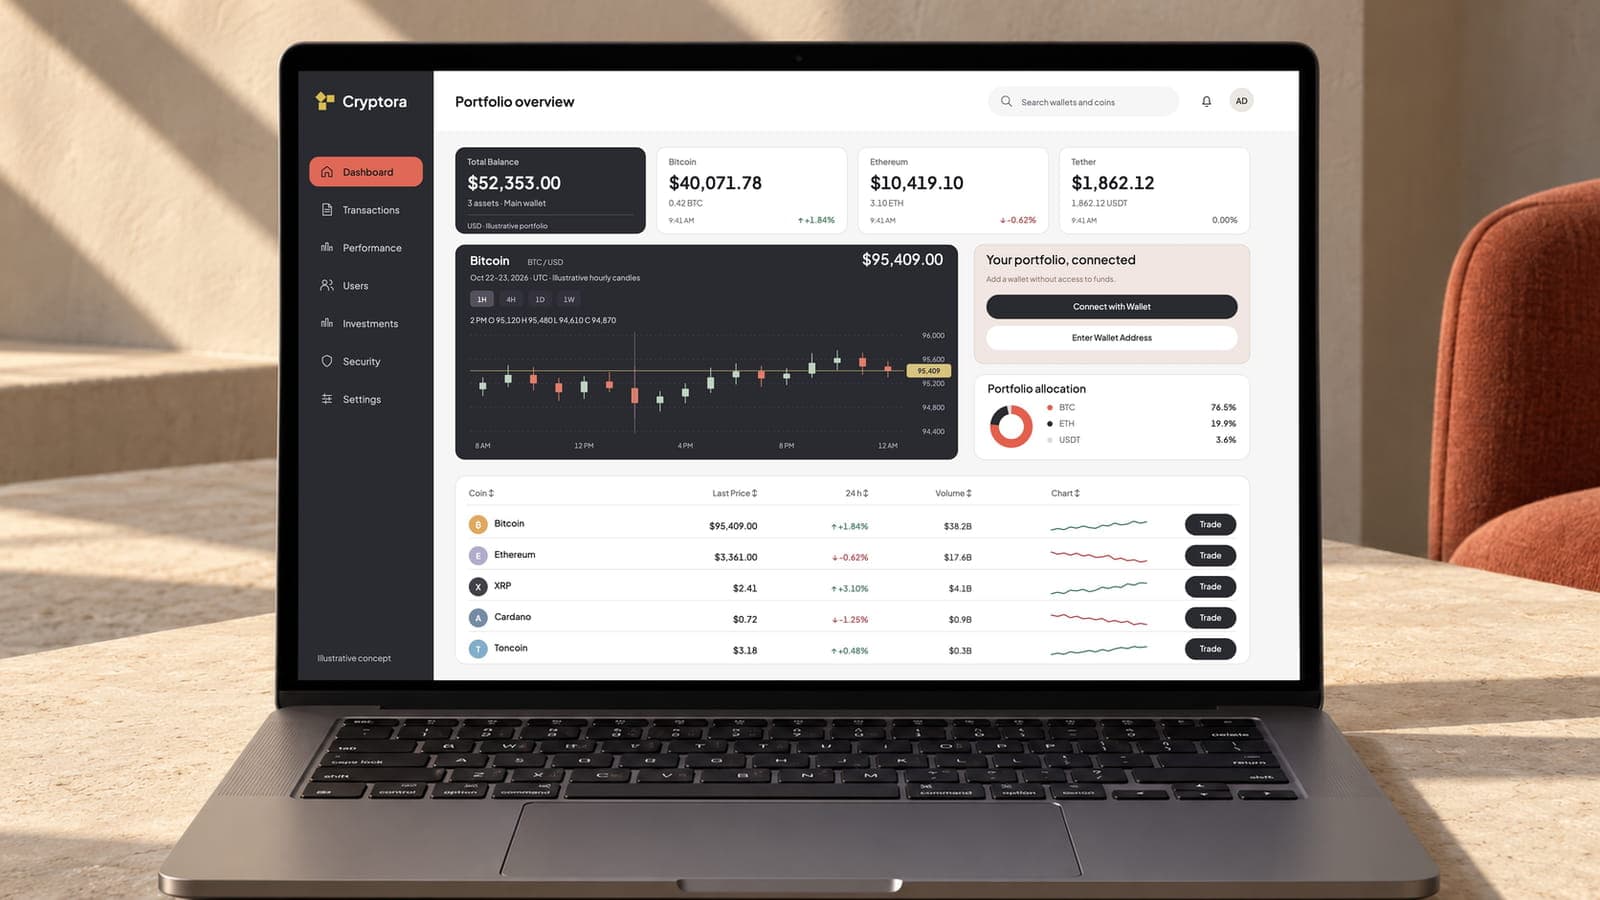
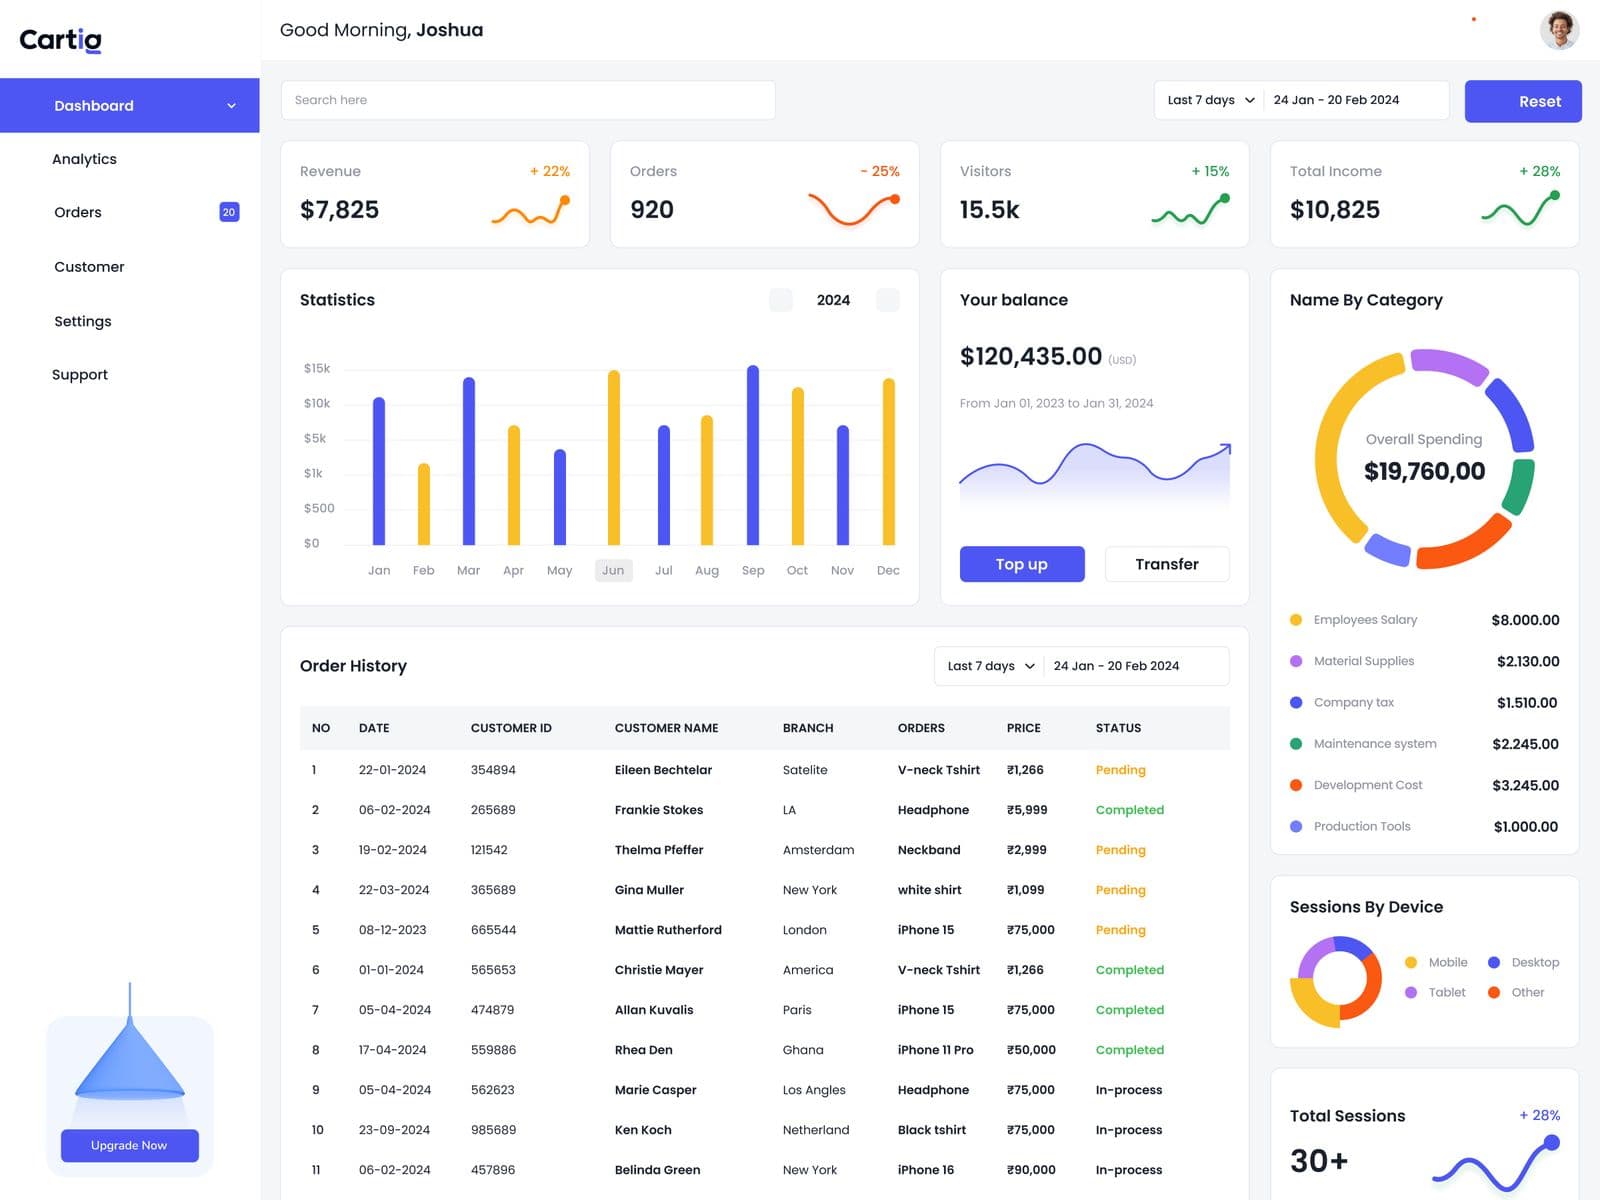
Crypto dashboard design and development for a portfolio tracker: Cryptora
A crypto portfolio dashboard, and the wallet sync, prices and ledger behind it.
Fintech software development company services
Our custom fintech software development services
We build six kinds of system, each on the partners and rails your product depends on. The work spans fintech, lending and banking software development.
Payments and wallets
We build checkout, payment gateway integrations, payouts and mobile wallet features on tokenized APIs, so card data stays off your servers.Lending platforms
We put loan origination and servicing in one workflow: applications, documents, decisions from your credit partner, repayments and collections.Wealth and investment tools
We build wealth management portfolio views, client onboarding and reporting on your custodian’s or broker’s APIs, so the assets stay with them.Onboarding and KYC flows
We route identity verification and screening through a specialist provider, and keep the audit trail your compliance team will be asked for.Back-office and reconciliation
We build ledgers, reconciliation against bank and processor reports, and the exception queues your finance team works through every day.Reporting and compliance data
We draw regulatory and management reporting straight from the ledger, so month end no longer depends on spreadsheets assembled by hand.
Client reviews
Rated 5.0 by the companies we build for
Saurabh GoswamiManaging Director, Ultra Rich Weddings 5/5★★★★★“Redlio Labs successfully delivered the project within schedule; they met all of our requirements. Their quality designs and in-depth knowledge of technology were key elements of their work.”
 Verified review on Clutch
1 / 4
Buyer’s checklist
What to settle before your fintech build starts
The decisions, comparisons and checks we work through with every buyer. Put them to any supplier, us included.
Seven questions to settle before your fintech software build starts
We advise getting these answered in writing by any fintech software vendor, including us. The PCI Security Standards Council publishes what counts as cardholder data and why reducing scope matters.
- Which licensed partner performs each regulated activity: holding funds, processing cards, lending, identity checks.
- Whether card data will ever reach your servers, and if not, how the design keeps it out.
- Which system is the ledger of record, and how it is reconciled against the bank and processor every day.
- What happens when a partner’s webhook arrives twice, late or never.
- What your compliance team will need to evidence, and where the audit trail for each decision lives.
- Which data you may keep, for how long, and where it is hosted.
- Who owns the partner accounts, the keys and the code when the engagement ends.
We answer these with your team first, and most of the architecture follows from them. Left open, they are decided by the architecture, usually in the most expensive direction.
How we plan fintech integrations, partner by partner
A fintech product borrows most of its behavior from partners, so most of its risk arrives through their interfaces. We scope each of the five usual counterparts below, and the trouble each one tends to bring.
| Counterpart | Usual interface | What goes wrong |
|---|---|---|
| Payment processor | REST APIs, hosted fields, webhooks | Webhooks that arrive late, twice or out of order |
| Banking partner | Banking APIs, file transfers, ISO 20022 messages | Settlement files that do not match what the API reported |
| Identity and KYC provider | REST APIs, SDKs | Manual review queues nobody sized |
| Credit bureau or lending partner | Partner APIs | Decisions that must be explained to the customer, not just stored |
| Accounting and ERP | APIs, scheduled exports | Two ledgers that drift apart a cent at a time |
We apply one discipline to all five: we treat every partner message as something that can arrive late, twice or not at all, and reconcile against the partner’s own reports. Our custom software development work runs on the same rule: the integrations are scoped before the price.
What PCI DSS, KYC, SOC 2 and DORA change in a fintech software build
Security and compliance in fintech belong to the regulated entity. We build the software to keep your scope small and your evidence easy to produce.
- PCI DSSUnder PCI DSS, any system that stores, processes or transmits card data is in scope. We use tokenized checkout and hosted payment fields to keep raw card numbers off your servers, which shrinks what has to be assessed.
- KYC and AMLThese obligations, built on the FATF Recommendations in most countries, sit with the regulated entity. We build the verification flow through a specialist provider, the screening records and the audit trail an examiner will ask for.
- SOC 2 reportsBanks and enterprise buyers often ask their vendors for a SOC 2 report. It describes the controls around your systems, so we put logging, access control and change management into the build from the start.
- DORA (EU)Since January 2025, DORA requires EU financial entities to manage ICT risk, including the third parties they rely on. For products sold to EU financial firms, we plan for their questions about resilience, incident reporting and exit plans.
Who you’ll work with
The engineers you talk to are the engineers who build it
A team in Ahmedabad, India, working with clients around the globe. No account layer between you and the work.
- 2014
Building software since
Twelve years of systems for clients around the globe.
- 20
People on the team
Engineers, designers and project managers in one office.
- 6+
Years per engineer, minimum
Every engineer has 6+ years of experience. Project managers have 12+.
- 35+
Systems in production
Still running for the clients who commissioned them.
- 5.0
On Clutch and Google
15 Clutch reviews and 32 Google reviews, all public.
- 12h
Reply to every inquiry
And a written scope within 48 hours of the call.
Why Redlio Labs
Why companies choose us for fintech software development
Perimeter first
Card data, funds and licensed decisions left with your partners.
Partner by partner
Every integration planned against the partner’s own rules.
Security in the design
Encryption, roles and audit trails agreed before code.
Direct access to engineers
You talk to the people building it, from the first call.



Talk to the engineers and designers who would do the work.
Talk to our teamFintech software development process
From first call to your first stage live
A clear clock from the moment you contact us.
12hours
Within 12 hours of your message
01Talk to our team
Tell us the product and which bank, processor or lender it runs on. You speak with the engineers who would build it.
- NDA before the call
- 30-minute call
48hours
Within 48 hours of the call
02Receive your proposal
A written plan for discovery, a timeline and a price. Build, buy or extend: a straight answer.
- Discovery plan
- Timeline
- Price
Day 1
From sign-off
03Start delivery
We map the perimeter and every partner API, then build in stages against their sandboxes.
- Perimeter mapped
- Partner sandboxes
- Staged release
Industries
Other sectors we build for
Each sector brings its own data rules, auditors and systems. We build to them.
Healthcare
Patient and clinical software that starts with the record: who holds it, under which agreement, and how it reaches your EHR.
What we build for healthcare
- Patient portal development
- EHR and EMR integration
- Clinical workflow tools
- Telehealth and remote care
- Billing and revenue cycle management
- Data and reporting
Manufacturing
Software for the gap between what the ERP planned and what the machines actually made.
What we build for manufacturing
- Production planning and scheduling
- Manufacturing execution and shop floor data
- Quality and traceability
- Inventory management and material flow
- Maintenance and predictive maintenance
- ERP for manufacturing: integration and extensions
Logistics
Freight, fleet and warehouse software built for the shipments that go off plan.
What we build for logistics
- Transportation management systems (TMS)
- Warehouse management systems (WMS)
- Fleet management and dispatch
- Customer and partner portals
- Order and inventory management
- Freight billing and reconciliation
Retail
Tills, stockroom, warehouse and online store selling from one stock figure, one price and one customer record.
What we build for retail
- POS integration and store checkout
- Inventory across stores and warehouse
- Click and collect, ship from store and returns
- Loyalty, pricing and promotions
- Store staff apps
- Retail ERP and supplier integration
Ecommerce
Stores connected to the ERP, warehouse, trade price lists and tax rules behind them.
What we build for ecommerce
- Custom ecommerce storefronts
- B2B ecommerce website development
- Headless ecommerce development services
- ERP, inventory and order integrations
- Ecommerce marketplace development
- Ecommerce app development
Real Estate
Brokerage and property software that respects MLS rules and the money held for others.
What we build for real estate
- Property search and listing websites
- Real estate app development
- Property management software development
- Tenant and owner portals
- Custom real estate CRM software development
- MLS, payment, e-signature and accounting integrations
Education
Learning and student software that starts with whose data it is and how it reaches the LMS.
What we build for education
- Custom LMS development
- LMS integrations and LTI tools
- Student and parent portals
- School and university websites
- Education mobile apps
- Admin dashboards and reporting
Fintech software development company FAQs
Not answered here? Ask our team directly.
Talk to the people who do the work
Speak with the team that would lead your project. We respond within 12 hours and can sign an NDA before the call.
Prefer email?info@redliolabs.com
What does a fintech software development company do?
As a fintech software development company, we build the software financial products run on and integrate it with the banks, processors and providers that hold the licenses. That covers payments, lending, wealth, onboarding and back-office systems, plus the web and mobile apps customers use.
We are a fintech app development company as well. We build the app together with the ledger and the partner integrations, because the app is only as reliable as what sits behind it.
How much does fintech software development cost?
We price fintech software development on three things: the number of partners to integrate, the reconciliation involved and the compliance evidence required. Each additional partner, market or regulated feature adds work, mostly in integration testing and approvals. We do not publish prices; our guide to what decides custom software cost explains why quotes for the same product differ.
Do we need a banking license to build a fintech product?
Often a banking license is not needed to build a fintech product, and we design for that. Many fintech products work with a licensed partner that holds the funds or performs the regulated activity, and build the customer experience around it. Which licenses a product needs is a question for a regulatory lawyer, answered before we design the architecture.
How do you handle card data and PCI DSS?
We keep card data away from your systems wherever possible. We use tokenized checkout and hosted payment fields from your processor, so raw card numbers go to the processor and not to your servers. That keeps most of your software out of PCI DSS scope.
Can you integrate with our bank or payment processor?
Yes, we can integrate with your bank or payment processor, through their APIs, their files or both. We build every integration expecting messages to arrive late, twice or not at all, and reconcile against the partner’s own reports. We scope each integration before the price.
How long does custom fintech software development take?
We give you a timeline after discovery, once the perimeter is drawn and each partner is named. A focused fintech product on one partner can take a few months. Each additional partner, market or regulated feature adds time, mostly in integration testing and approvals.
Do you offer banking software development?
Yes, we offer banking software development for the systems around a licensed bank or banking partner. That means mobile banking apps and digital banking front ends, onboarding and KYC flows, ledgers, reconciliation against bank reports, and reporting. We connect to the core banking system through the APIs or files the bank exposes, and the license, the funds and the regulated activity stay with the bank.
We can also modernize legacy banking and lending systems in stages, with both systems running and their outputs compared until they agree. Our application modernization service page explains how.
Can you build a mobile banking or digital wallet app?
Yes, we build mobile banking apps and digital wallets in Flutter, React Native, Swift or Kotlin, on top of the bank or licensed partner that holds the accounts. Balances, transfers, money transfer between customers, card controls and currency exchange all run through that partner’s APIs, so the app shows and requests, and the partner moves the money.
Most of the work sits behind the screens: sign-in and device binding, handling a transfer that the partner confirms late, and the audit trail each action leaves.
Which tech stack do you use for financial software development?
For financial software development we usually build web products in Next.js, React and Node, with PostgreSQL for the ledger because it keeps transactions consistent, and mobile apps in Flutter, React Native, Swift or Kotlin. We host on AWS, Azure or Google Cloud, in the regions your regulators and partners expect.
Where your team already runs one of these, we follow its conventions. The choice of partners and where the regulated perimeter sits shapes the architecture far more than the framework does.
Who owns the code and the partner accounts?
We advise every client to own the code and the partner accounts. The code, the cloud accounts, the partner accounts and the keys should be in your name, written into the contract before the work starts. We suggest asking any fintech software vendor to put that in writing, including us.
When is fintech software development the wrong choice?
We advise against a custom build in three cases, and we say so on the first call:
A banking-as-a-service platform covers it: Where a licensed platform already offers the accounts, cards or payments through its API, we advise building the customer experience on top and leaving the core to it.
The product is a standard ledger: Accounting and standard lending products are mature. We recommend configuring one and keeping the build budget for something else, unless your product logic differs.
No one to staff the compliance side: Custom software means your own team evidences its controls. Without someone to own that work, we recommend a regulated platform, which carries the load better than a build would.
We recommend custom fintech software where the product logic, the customer experience or the reconciliation between partners is what makes your business different.
Tell us about your fintech build
Share what the system has to do and what it connects to. You’ll talk to the engineers who would build it and get a straight answer on fit. We reply within 12 hours.
- We reply within 12 hours
- A quote within 48 hours of the scoping call
- Direct access to the delivery team
- Peer-reviewed releases
- NDA before your first call
Mayursinh Jadeja
Founder, Redlio Labs